Search


HUF Tax Benefits: How Hindu Undivided Families Save Tax In India
 320

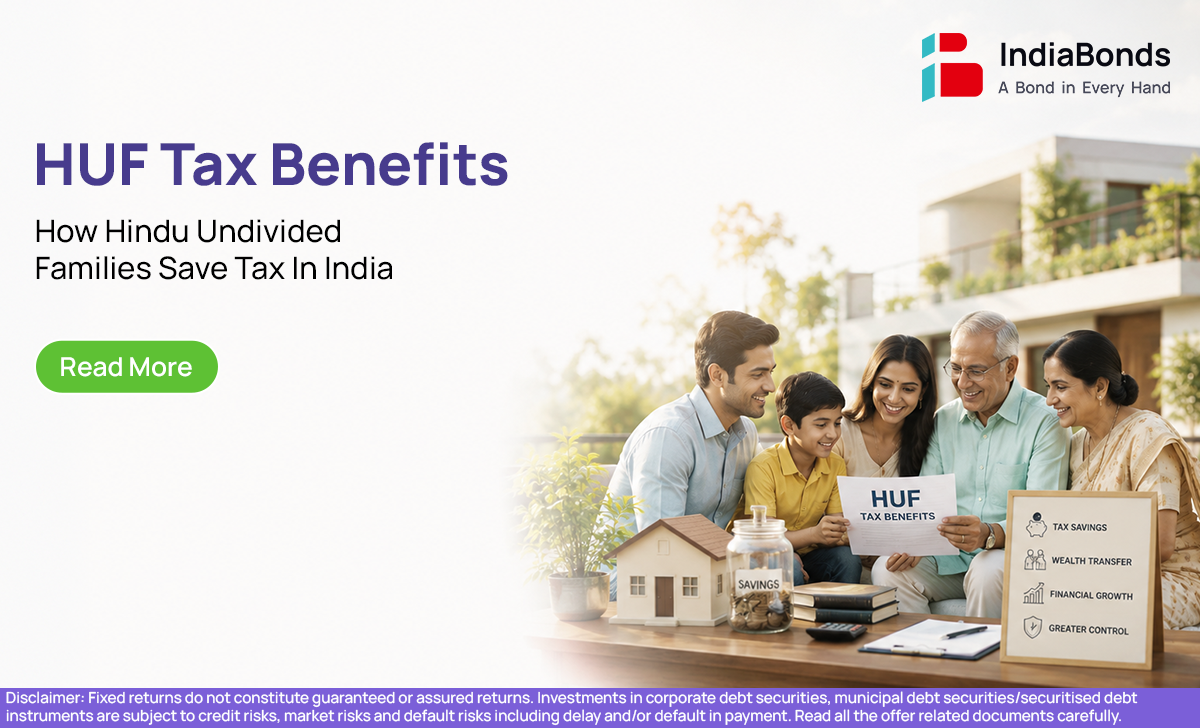
Many families today actively look for legitimate, time-tested avenues to optimize their financial outgo. In a complex fiscal environment, understanding the subtle nuances of the tax code is essential for long-term wealth preservation and growth. One powerful, yet often overlooked, mechanism for systematic wealth management is the Hindu Undivided Family. When families structure their finances correctly, they can leverage significant HUF Tax Benefits to ensure that collective family resources are managed with greater efficiency. By utilizing these provisions, families can build a more secure future, ultimately leading to improved long-term financial health and sustainable growth through strategic, informed decision-making.
Key Tax Benefits of HUF
Operating as a separate legal entity grants the family a distinct identity under the Income Tax Act, allowing it to be assessed separately from its individual members. This structure essentially creates an additional tax-paying unit, which brings several strategic advantages for those seeking to optimize their financial landscape. Many experts emphasize that one of the most significant HUF Tax Benefits is the ability to create a separate pool of income.
- Separate Exemption Limit: Since an HUF is recognized as a separate tax entity, it enjoys its own basic exemption limit. This means income earned by the HUF is taxed independently, often at lower slabs compared to the combined income of family members.
- Dual Benefit for Members: Individuals can continue to earn their own income while the HUF generates its own returns from its dedicated investments. This strategy helps in distributing the total family income across two distinct entities, preventing income from bunching into higher tax brackets and thus maximizing the overall efficiency of the family’s financial planning.
- Asset Segregation: By pooling ancestral or family assets, one can streamline management and tax filing. This structured approach simplifies the process, ensuring that family wealth is handled with professional diligence and clarity. Families often find that these HUF Tax Benefits provide a much-needed layer of protection and organization for their shared financial assets.
Tax Deductions Available to HUF
The Income Tax Act provides a variety of deductions that families can utilize to reduce their overall taxable income. By incorporating strategic HUF tax planning, families can maximize these allowances effectively. The Karta, acting as the manager of the HUF, plays a pivotal role in ensuring that all investments are made in the name of the HUF to claim these deductions appropriately.
| Deduction Section | Description | Eligible Amount/Limit |
| Section 80C | Investments in PPF, ELSS, NSC | Up to ₹1.5 Lakhs |
| Section 80D | Health insurance premiums | Limits apply based on age |
| Section 80G | Donations to charitable funds | As per notified limits |
When utilizing these deductions, it is crucial to remain updated on the latest Hindu undivided family tax rules. Proper documentation is mandatory to ensure these claims hold up during any assessment proceedings. By adhering strictly to these guidelines, the Karta ensures that the family remains compliant while enjoying the full spectrum of available tax-saving opportunities. Furthermore, sound management requires that the Karta keeps detailed records of all financial transactions, as these are vital for maintaining the integrity of the HUF’s tax filings and following all relevant Hindu undivided family tax rules.
Individual vs HUF Tax Liability Comparison
Understanding how an HUF functions as a distinct structure compared to an individual’s tax liability is vital for any family aiming to optimize their fiscal outcome. The table below illustrates the conceptual difference in how tax liabilities are managed for individuals versus a collective unit.
| Feature | Individual | Hindu Undivided Family (HUF) |
| Tax Status | Single taxpayer | Separate tax entity |
| Exemption Limit | Standard slab | Independent slab |
| Asset Ownership | Personal | Family pool |
| Tax Filing | Individual return | Separate PAN required |
By treating the HUF as a HUF separate tax entity, families can effectively lower their total tax burden. This approach is highly effective for HUF tax saving in India, especially for families holding significant rental property or investment portfolios that can be transferred to the family pool. Additionally, recognizing the HUF as a HUF separate tax entity is a fundamental step in ensuring that the family’s financial activities are legally and tax-efficiently segregated from personal earnings. When executed correctly, these strategies are instrumental for successful financial optimization.
Investment Options For HUF
When it comes to building a robust and diversified portfolio, the HUF has access to a wide array of financial instruments. Decisions should always align with long-term goals while keeping the focus on tax efficiency and risk management.
- Fixed Deposits & Debt Instruments: Utilizing corporate deposits or high-yield bonds allows the family to generate steady returns. These investments often form the backbone of a conservative strategy, providing stability to the family portfolio.
- Mutual Funds: Investing in diversified equity or debt mutual funds through the HUF PAN provides the benefit of professional management and potential for capital appreciation over the long term, further enhancing the overall HUF Tax Benefits.
- Direct Equity: Investing in stocks allows the HUF to participate in market growth, provided the risks are thoroughly evaluated and managed by the Karta in consultation with family members.
Effective management involves choosing instruments that provide both growth and tax-efficient returns. By diversifying investments across these categories, the family can build a resilient portfolio that supports its long-term financial objectives, effectively compounding the various HUF Tax Benefits available to them.
Conclusion
Navigating the complexities of wealth management requires a clear, strategic understanding of the legal frameworks available. By leveraging the inherent HUF Tax Benefits and staying informed about the evolving landscape of tax management, families can create a structured, professional approach to wealth preservation. Consulting with financial experts ensures that these strategies are implemented in full compliance, ultimately providing peace of mind and long-term financial security for the entire family unit.
FAQs
What are HUF tax benefits?
The primary benefits include a separate tax exemption limit and the ability to claim deductions under various sections like 80C and 80D, as the HUF is taxed as an independent unit, separate from the individual members.
Can HUF save tax?
Yes, by acting as a separate tax entity, an HUF allows income to be distributed, effectively moving income out of the higher personal tax slabs of its members and into a potentially lower-taxed unit.
Is HUF legal in India?
Yes, the Hindu Undivided Family is a legally recognized entity under the Income Tax Act, 1961, and is widely utilized for professional family wealth management and long-term financial structuring.
Disclaimer: Fixed returns do not constitute guaranteed or assured returns. Investments in corporate debt securities, municipal debt securities/securitised debt instruments are subject to credit risks, market risks and default risks including delay and/or default in payment. Read all the offer related documents carefully.
320